
Which Pin Retention Method Should You Use for a Clevis: Clip, Split Pin, Circlip or Locking Pin?
Use a split (cotter) pin for a joint you rarely open, and a reusable clip such as an R-clip for one you open often. A circlip works where the pin has a groove for it. A bolt with a self-locking nut also works if the thread is outside the shear plane. Every method is a […]
How Do You Press-Fit and Retain a Plastic Bushing Without Cracking It, and What Interference Does It Need?
The maker builds the interference into the bushing, so your job is the housing bore: hold the maker’s tolerance, chamfer and deburr the edge, press the bushing in square with a flat press, and measure its bore only after it is in. A pressed-in bushing closes in by roughly the amount of the interference, so […]
Freight Rates Ease at the Margin but Stay Historically High
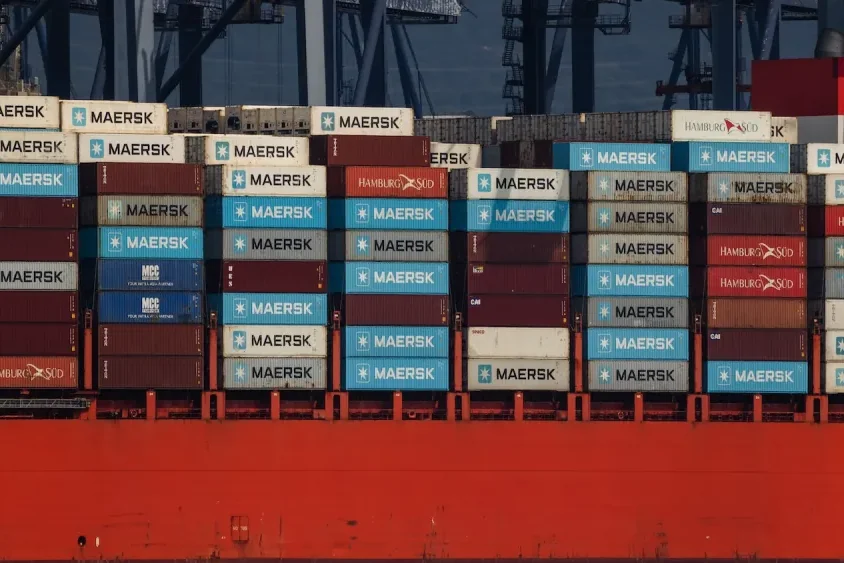
Container shipping rates remain roughly 124% above year-earlier levels even after a modest weekly decline, and Maersk has raised its 2026 outlook for a third time — a signal that port congestion and AI-related cargo demand are still shaping delivery schedules and landed costs for industrial parts. In Washington, the US is pressing Beijing to “immediately” honor rare-earths commitments under the Busan trade framework, while copper prices slipped on fears of an AI infrastructure backlash. OpenAI responded to local opposition by pledging to cover electricity and grid costs for its data centers, a template that could influence how power-intensive projects get permitted. Elsewhere: Liebherr added a 250-tonne electric excavator, South Korea is funding smart-factory upgrades in Vietnam, St. Paul voters approved a right-to-repair ordinance, and India’s factory PMI eased while investment in plant capacity continued to climb. This week’s briefing connects those threads for component buyers, engineers, distributors, and manufacturers.
How Do Oscillation Angle, Frequency and Sliding Speed Determine the Life of a Spherical Plain Bearing?
A spherical plain bearing wears where its two surfaces slide on each other, so its life depends on how far and how fast they slide, and how hard they press. The swing angle and the swing rate set the sliding speed. The load and the size of the bearing set the contact pressure. Pressure times […]
Which Thread Size, Pitch, Class and Hand Should You Specify on a Linkage Rod, Turnbuckle or Jack Screw?
Give four things, in this order: the nominal diameter, the pitch (or threads per inch), the class of fit, and the hand (right or left). Write inch threads like 3/4-16 UNF-3A and metric ones like M10 × 1.5 – 6g, and add LH for a left-hand thread. Make the thread match the part that screws […]
What Compliance Documents Should I Ask for When a Plastic Bushing Is Used in a Food Plant?
Ask the bushing maker for a written statement that the exact grade meets the food-contact rules for your market. In the US that means the 21 CFR section it falls under, a certificate of conformance or letter of guaranty, the resin grade and whether it is virgin, proof that the additives are listed, and migration […]
Machinery Tariffs Deferred: A Negotiating Window, Not a Resolution
Washington has labeled imported robots and industrial machinery a national security risk but deferred tariffs and quotas in favor of negotiated outcomes — a pause, not a reprieve, for anyone buying machine tools or automation hardware. China’s October manufacturing PMI fell to 49.3, keeping the world’s largest equipment-producing base in mild contraction even as high-tech segments expand. Steel pricing is firming in Europe and India is pouring policy money into specialty steel, while rare-earth supply policy shifts across Brazil, Australia and the United States. On the demand side, grid and data-center infrastructure spending is now the clearest growth signal for heavy equipment and components, and freight markets are diverging by region. This week’s briefing connects those threads for component buyers, engineers, distributors and manufacturers.
How Do I Inspect the Welds Around a Ball Socket for Fatigue Cracks, and Can It Be Repaired?
Clean the area and look first. Cracks start at weld toes, corners and holes, and rust stains or broken paint along a weld can show a crack opening and closing. Confirm anything suspicious with a non-destructive test such as magnetic particle or dye penetrant. Cracks are not normally accepted in welds, and a socket on […]
Why Does a Rod End Wear, Develop Play, Bind, Squeak or Seize, and How Do I Find the Cause?
Almost every rod end problem comes from one of six things: poor installation, too little grease, dirt and water getting in, overload or shock, misalignment, or a harsh environment. They often work together. Read the symptom first, because each one points to a wear mechanism. Then trace back to the first fault in the chain, […]
Should You Replace Only the Spherical Bearing or the Whole Rod Eye on a Hydraulic Cylinder?
Replace only the bearing when it is held by removable retaining rings, the eye’s bore is round and undamaged, and the bearing has not turned in its seat. Replace the whole rod eye when the bearing is permanently staked in, the bore is out of round or damaged, or the bearing has spun in the […]
Freight and Energy Costs Reassert Themselves as Industrial Cost Drivers
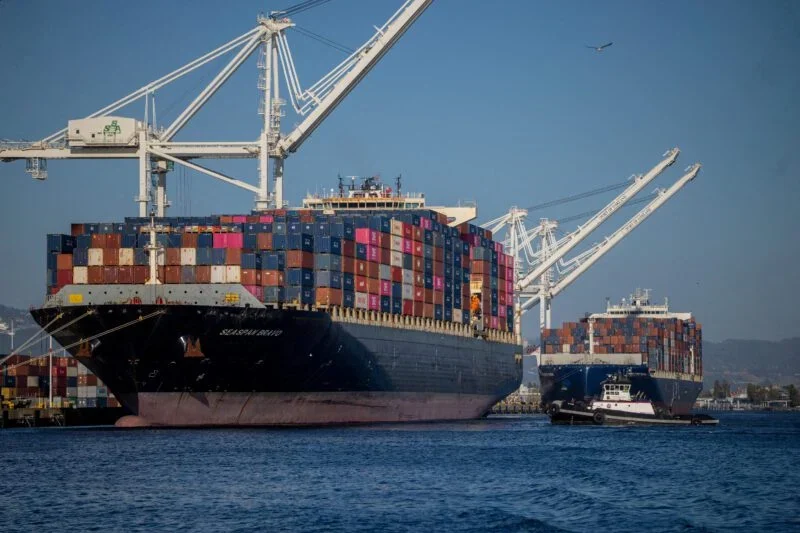
Global container freight rates have climbed roughly 130% since February as Red Sea security concerns and a super typhoon disrupt Asian port operations, while Brent crude briefly touched $114 a barrel — a combination that raises landed costs for machinery, castings and aftermarket parts. In materials, TSMC is reportedly surveying suppliers on rare-earth-free motors ahead of a Chinese export-control pause nearing legal expiry, Taiwan is planning a rare-earth processing plant, and Wood Mackenzie warns that AI-driven power demand is straining metals supply. On the demand side, US flash manufacturing PMI hit a 53-month high in October while Japan’s fell to a seven-month low and India’s growth slowed, underscoring a widening regional divergence. Trade policy remains active: the USTR proposes extending its China-linked port fee suspension into January 2027, Washington is weighing wind-turbine negotiations rather than tariffs, and the EU’s carbon and “Made in EU” rules are drawing pushback from India and Turkey. This week’s briefing covers freight and energy costs, rare-earth and metals supply, regional manufacturing signals, automation and distribution consolidation, trade policy, and the right-to-repair debate.
Why Does an Adjustable Linkage Change Length Under Vibration, and Which Locking Method Works?
The thread inside an adjuster slowly turns when the joint is shaken from side to side or when the load reverses, even if nothing seems loose. The usual fix is a jam nut, a thin nut tightened against the end face of the part so the two lock each other. A thread-locking adhesive, or a […]