US Output Rebounds, but the Mix Matters More Than the Headline
US industrial production rose faster than expected in September, with manufacturing output rebounding on semiconductors and supplies — a signal that capital investment, not consumer demand, is carrying the current industrial cycle. Around that core data point, this week’s briefing tracks five connected shifts: a 3% rebound in global container rates after a 13-week decline, with Asia–Europe lanes leading and schedule reliability still weak; US–Mexico trade talks stalling as the USMCA review approaches; a widening EU split over the scope of the carbon border adjustment mechanism; heavy equipment order momentum in China and India alongside dealer-network consolidation in North America; and a rare-earths supply story moving from policy rhetoric to project timelines in Malawi, the US and Australia. For component buyers and engineers, the common thread is planning risk: freight costs are turning, trade rules are in flux, and the materials and power inputs behind automation and electrification are being re-sourced at project level rather than announced at strategy level.
Port Congestion Absorbs 12% of Global Container Capacity
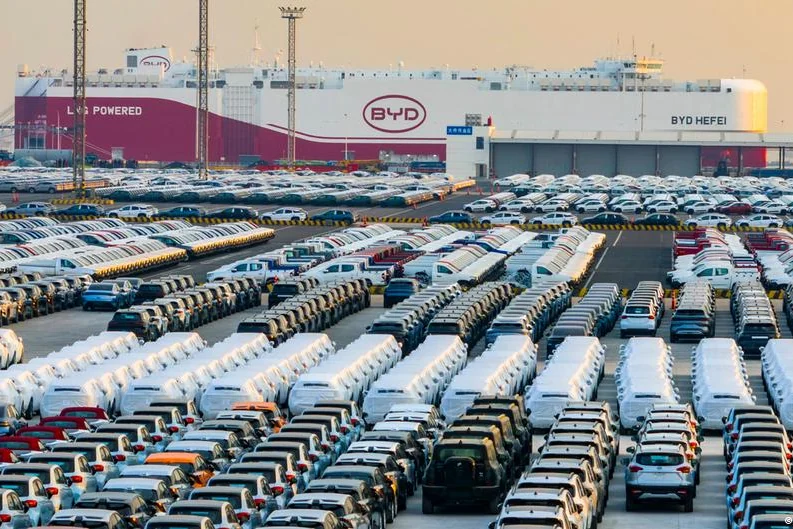
Global container capacity is being squeezed by congestion that now absorbs roughly 12% of the world fleet, extending peak season well past its usual window. At the same time, three regulatory tracks are converging on industrial trade: the EU’s carbon border mechanism is being priced into steel, the USMCA review has pushed trade uncertainty to multi-decade highs, and right-to-repair rules are advancing through courts and legislatures. On the demand side, the picture is uneven — Volvo CE reported a 14% second-quarter sales decline, US August industrial output came in flat, and several European economies posted weaker production, while AI-driven infrastructure spending and data-centre power demand keep setting records. Materials markets are mixed: rare earths remain a processing bottleneck outside China, but European steel pricing is firming. This week’s briefing covers freight capacity, trade policy, industrial demand signals, materials, automation standards, and the emerging right-to-repair regime.
Manufacturing Momentum Meets an Inflation Problem
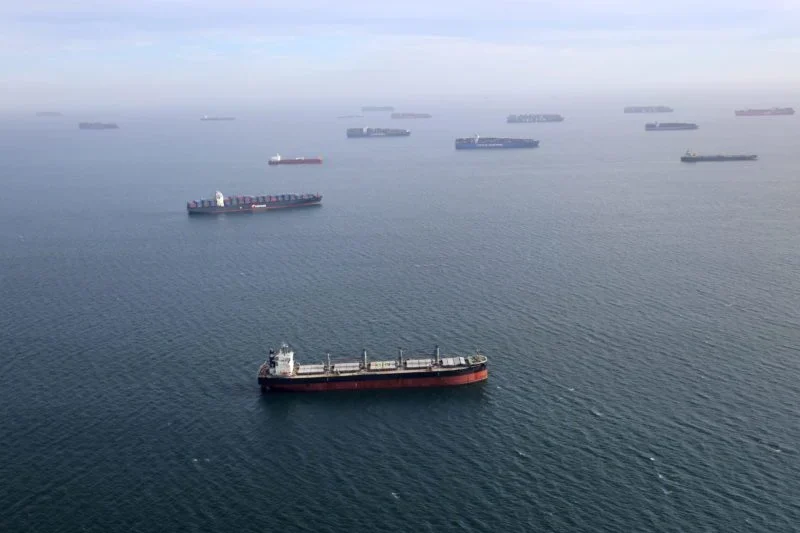
September’s global manufacturing PMI reached its highest level since February 2022, with India posting a seven-month high and U.S. factory activity expanding for a ninth straight month — but the same surveys show input prices accelerating, and diesel, freight and rare-earth costs are all moving in the wrong direction for buyers. Roughly 12% of the world’s container ship capacity is tied up in port congestion that could persist into 2027, Asia–Europe rates have now fallen for twelve consecutive weeks even as U.S. rates hit a post-Hormuz peak, and Saudi planning for a Red Sea offensive keeps the Bab el-Mandeb corridor in play. In materials, Lynas agreed to buy Meteoric Resources for $672 million to enter Brazil’s rare-earth sector, Rio Tinto expanded low-carbon aluminium billet supply, and aluminium prices touched a twelve-week low on dollar strength. Trade policy stayed active: the U.S.–China Section 301 pause was extended, USMCA talks edged forward, and CBAM compliance costs are spreading beyond steel into more export categories. This week’s briefing covers what changed, what is driving it, and what it means for the people who specify, buy, and move industrial components.
Trade Truce Extended, but the Fine Print Is Still Missing
Two forces moved in opposite directions this week. Washington and Beijing agreed to extend their trade truce into early 2027, unlocking tariff relief across a $30 billion basket of goods and easing pressure on importers. At the same time, traders began pricing in as many as four Federal Reserve rate hikes by mid-2027, pushing the dollar to an eight-week high and raising the cost of imported components, commodities, and capital equipment. Freight markets are tightening ahead of Golden Week, rare earth prices outside China keep climbing, and a wave of automation and reshoring investment — from SoftBank’s $225 million bet on autonomous construction to Amazon’s $100 million robotics plant — signals that manufacturers are still spending through the uncertainty. This week’s briefing covers the trade reset, the currency squeeze, freight and port conditions, materials costs, automation investment, and the regulatory shifts reshaping repair and safety rules.
Red Sea Pressure Builds as Bab el-Mandeb Risk Returns to the Fore
Three forces dominated industrial news in the week to September 21, 2026: a deteriorating security picture around the Bab el-Mandeb strait that is pushing ocean freight rates toward record levels, a rare-earths standoff running in parallel with US–China trade talks ahead of a White House summit, and a hawkish Federal Reserve that lifted the dollar index back above 100. Around those macro currents, the week brought concrete capacity moves — XCMG’s first overseas mining-component remanufacturing base in Indonesia, Lam Research’s roughly $1 billion India expansion, and new plant openings in Vietnam and Serbia — plus a US manufacturing output reading that came in below consensus. This briefing covers the freight, materials, trade, energy and automation storylines that matter most to component buyers, engineers and distributors.
Red Sea Risk Returns: Pipeline Closure and Houthi Advances Raise Freight and Energy Stakes
Industrial buyers entered mid-September facing a rare convergence of pressures. Saudi Arabia shut its East-West oil pipeline after a drone attack while Houthi advances threatened Red Sea shipping, pushing energy and freight risk higher. Copper touched record highs on AI-driven demand and tariff uncertainty, even as rare-earth supply chains gained new processing and recycling capacity in Brazil and the United States. In manufacturing technology, AI moved deeper into the plant floor — from robot drilling accuracy to additive-manufacturing design — while the EU’s right-to-repair regime and a US solar duty decision added fresh compliance and sourcing questions. Regional demand signals diverged: India’s manufacturing leasing boom and Hyundai’s North American local-sourcing target pointed to structural investment, while Türkiye’s industrial output slipped. This briefing covers the storylines most likely to affect component pricing, lead times, and sourcing decisions in the weeks ahead.
Diesel at Record Highs: A Cost Shock Across the Supply Chain
Global industrial supply chains are entering a period of acute stress as record-high diesel prices collide with severe port congestion in Asia and the Panama Canal. Simultaneously, the rare earths sector is undergoing a strategic realignment, marked by new US recycling investments, Chinese export hesitancy, and Brazilian regulatory shifts. This week’s briefing examines the forces driving these changes and their implications for manufacturers, distributors, and equipment buyers navigating rising costs and extended lead times.
Record Port Congestion and the $10,000 Container
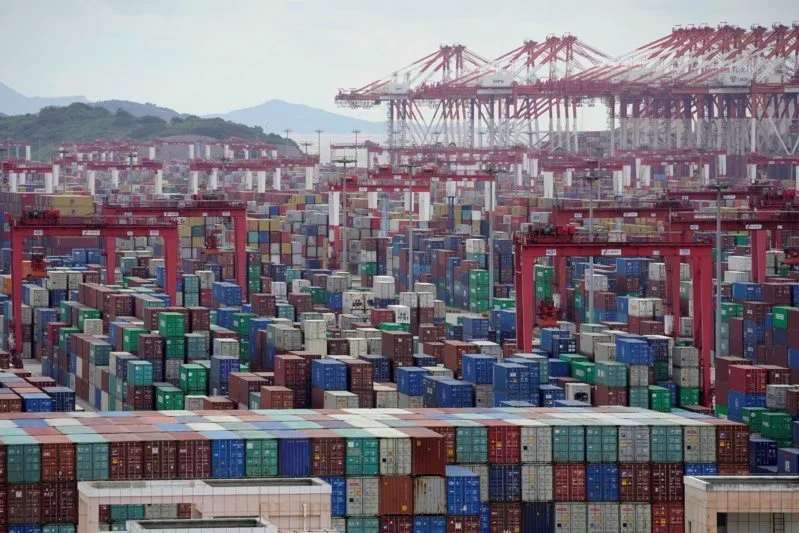
Global container shipping is under severe strain, with port congestion reaching a record 4.3 million TEUs and trans-Pacific freight rates spiking to two-year highs, including $10,000 per 40-ft container on the India-US lane. This week’s intelligence shows that the convergence of tariff-driven front-loading, typhoon disruptions in China, and vessel redeployments is creating a logistics bottleneck that directly impacts industrial component buyers, OEMs, and distributors worldwide. Concurrently, raw material markets are signaling new cost pressures: Toyota and Nippon Steel have agreed on the first steel price hike in four years, aluminum billet processing fees in China have plunged below cost lines, and rare earth supply chain diversification efforts are accelerating. Meanwhile, the US dollar’s strength, driven by hawkish Fed signals, is adding another layer of complexity to global procurement strategies. This briefing analyzes these interconnected developments and their implications for the industrial parts ecosystem.
North American Trade War: The September 8 Retaliation Deadline
The escalating US-Canada trade dispute, now set for a September 8 retaliation date, is forcing a hard reset on North American industrial supply chains, with agricultural equipment, steel, and electronics in the crosshairs. Simultaneously, global logistics networks are straining under a 4% weekly jump in container rates, persistent Red Sea disruptions, and record port congestion in Asia. This week’s intelligence also highlights a decisive shift toward electrification in heavy mining equipment, new momentum in the right-to-repair movement for off-road machinery, and a widening gap between AI infrastructure investment and near-term industrial demand.
Autonomous Equipment Moves From Pilot Projects to Funded Reality
Executive summary. Autonomous heavy equipment moved from pilot project to funded reality this week: Gravis Robotics closed a $200 million Series A led by SoftBank — the largest such round in construction equipment history — while Bedrock Robotics, founded by Waymo veterans, said its self-operating excavators are already working across three sites in Texas and Nevada. In freight, Maersk’s chief executive described port congestion as a “structural part” of global supply chains, and Asia–US East Coast container rates hit a 2026 peak. BHP posted a 30% profit jump on record copper prices, right-to-repair advocates scored major wins for US farmers, and Washington expanded Section 232 tariffs to drones and polysilicon as the USMCA review intensified. A softer dollar and mixed Asian output data completed the picture.
The $1 Trillion AI Infrastructure Wave Reaches Deeper into Industrial Supply Chains
Executive summary: This week’s industrial intelligence points to a bifurcated global market. On one hand, AI data-center buildout continues to drive unprecedented demand for power generation, grid components, and heavy equipment, with cumulative infrastructure spending surpassing $1 trillion. On the other, traditional industrial end-markets show strain: China’s steel prices hit a near-decade low, Brazil’s industrial output contracted sharply, and the US dollar’s slide is resetting competitiveness dynamics. Trade policy remains a dominant variable, with new Section 232 tariffs on polysilicon, a third round of Section 301 tariffs, and the looming 2026 USMCA review forcing supply chain recalibration. Meanwhile, right-to-repair legislation is gaining ground in the US agricultural sector, and rare earths supply chains are seeing strategic realignments from Australia to Kazakhstan. For component buyers and manufacturers, the takeaway is clear: resilience now depends on navigating both the AI-driven demand surge and the fragmented trade landscape.
Red Sea Security Crisis and Container Rate Swings Test Supply Chains
Geopolitical and policy shifts are jolting industrial supply networks this week. Saudi Arabia is building an international naval coalition to safeguard Red Sea transit just as container rates slide for a third week and carriers prepare August rate hikes. On the regulatory front, landmark right‑to‑repair settlements and new EU rules promise to remake equipment aftermarkets, while trade policy uncertainty sharpens with the lapsing US‑Mexico‑Canada Agreement and fresh Section 301 tariffs hitting 60 trading partners. Materials markets are equally turbulent: rare‑earth supply chains are diversifying, copper prices are spiking on Chilean mine disruptions, and steel remains mired at 15‑year lows. Simultaneously, AI infrastructure spending is reaching historic highs, driving demand for power equipment and automation, while factory‑floor technology leaps forward with wireless connectivity and predictive maintenance. Global manufacturing readings are mixed — China’s factory output contracts unexpectedly, Japan edges higher, and near‑shoring gathers pace. Off‑highway and powersports demand stand out as bright spots, with recreational vehicle revenue soaring and e‑bike sales hitting new milestones. For component buyers, engineers and distributors, these converging forces will reshape lead times, cost structures, and sourcing strategies well into the second half of 2026.